 Crypto.
 Σχετικά
 Passport
 Conference call
 send money
 Όρους
 Ιδιωτικότητα
 Sierra market
Europe Solar PV Energy: Understanding Market Growth and Commercial Potential
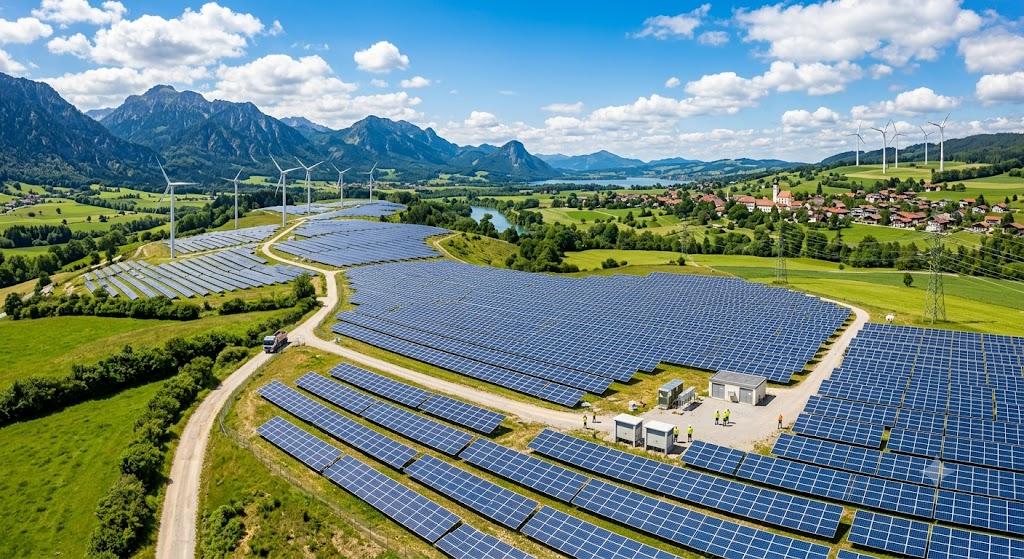
How Europe’s Solar PV Market Is Reshaping Renewable Energy
Europe’s photovoltaic industry is increasingly shaped by a combination of energy policy, electricity-market reform, grid investment, and changing customer economics. The sector is moving beyond a simple race to add panels. Developers and asset owners now have to consider connection capacity, local power prices, curtailment, contract structures, and the timing of cash flows when evaluating new projects.
The long-term demand case remains supported by Europe’s decarbonization objectives and the need to diversify electricity supply. Solar can be installed quickly compared with many large generation projects, and its modular nature allows deployment from individual homes to multi-hundred-megawatt plants. This flexibility gives photovoltaic technology an important role in meeting additional electricity demand while reducing exposure to fossil fuel volatility.
Yet deployment volume does not automatically translate into stable project returns. Solar generation often peaks during hours when many photovoltaic assets are producing simultaneously. In markets with substantial penetration, this can place downward pressure on daytime wholesale prices. Increasing occurrences of zero or negative prices make captured-price analysis essential, especially for merchant projects and contracts that do not fully protect producers from market exposure.
Grid constraints add another layer of complexity. Developers may secure land, permits, equipment, and financing while still waiting for network reinforcement. Distribution and transmission bottlenecks can restrict exports or require projects to operate below their theoretical output. Consequently, grid connection should be assessed as an execution process with dependencies rather than treated as a simple administrative milestone.
Different customer segments are responding in different ways. Residential installations depend strongly on household electricity bills, financing availability, incentive structures, and compensation for exported power. Commercial and industrial customers can benefit from self-consumption because solar production overlaps with daytime business demand. Utility-scale developers, meanwhile, must optimize land, interconnection, financing, offtake, and market exposure at much larger scale.
Corporate power procurement is another important growth channel. Companies seeking renewable electricity may use physical or virtual power purchase agreements to secure long-term supply attributes and manage energy costs. These arrangements can support new solar projects, but their value depends on contract duration, pricing, volume commitments, settlement rules, credit quality, and the allocation of balancing responsibilities.
Storage is becoming increasingly relevant because it can alter the timing of solar output. Batteries may absorb electricity during low-value periods and discharge later when prices or system needs are stronger. Co-located storage can also provide flexibility around grid constraints, although connection rules and market access determine whether those benefits can be monetized. Developers therefore need to model solar and storage as an integrated operating system when appropriate.
Policy design will continue influencing investment. Auctions, support schemes, renewable targets, permitting reforms, and electricity-market rules can improve visibility, while frequent regulatory changes may increase uncertainty. Two-way contracts for difference are gaining attention as a mechanism that can stabilize revenues while retaining some market discipline. Their effect on project economics depends on design, strike prices, settlement conditions, and participation rules.
Technology suppliers are adapting to these conditions. Module efficiency remains important, but investors are also looking at inverter capabilities, digital controls, forecasting, monitoring, and grid-code compliance. EPC companies increasingly need strong interface management because protection systems, metering, export controls, and network requirements can create late-stage changes.
The Europe Solar PV Energy Market Analysis indicates a market where growth and risk must be considered together. Future opportunities are likely to favor projects with credible grid pathways, resilient offtake arrangements, flexible operating designs, and disciplined cost management. This creates room for developers, financiers, technology firms, aggregators, and service providers that can turn growing solar capacity into dependable energy infrastructure.
Geographic screening can distinguish scalable portfolios from projects exposed to congestion and weak revenues.
Bub
Do?

Κατηγορίες
Διαβάζω περισσότερα
The Runes of Aldur league introduces a large collection of mechanics that gradually become available through the Runeseeker Campaign Questline. For players managing their resources and planning purchases of Path of Exile 2 Currency, understanding this progression is particularly useful. Several important crafting features are locked behind campaign objectives, so simply completing the main...
The global box office landscape for "Star Wars: Episode II — Attack of the Clones" is showing signs of decline, with audiences overseas losing interest at a pace comparable to domestic trends. While the film initially performed strongly, recent figures reveal a significant drop, especially in European markets. In Germany, the film's third week saw a steep decline, leading local...
在數位化浪潮的推動下,線上娛樂產業逐漸從單一遊戲模式轉向多元化互動體驗。許多使用者開始關注平台的安全性、設計與參與感,而像 鉅城娛樂城 這類型的數位娛樂網站,也讓人們重新思考虛擬娛樂環境如何與現代科技融合。從產業角度來看,這不只是娛樂方式的改變,更代表了數位服務模式的升級。 線上娛樂平台的數位轉型趨勢 過去的娛樂網站往往以單一功能為主,但近年來,平台更重視整體體驗。從介面設計到社群互動,每一個細節都影響使用者的停留時間與滿意度。現代化的娛樂城系統通常結合即時資料分析與雲端技術,使內容更新更快速,同時也能提供更穩定的服務環境。 此外,數據導向的營運方式讓平台能夠理解用戶習慣,進一步優化功能。這種轉型不僅提高效率,也讓整體服務更貼近使用者需求,形成一種持續成長的數位生態。 使用者體驗如何影響選擇...
It's kind of crazy how GTA V refuses to slide into "classic" territory. Most games peak, then quietly drop off when the next big thing lands. Not this one. You still boot up your console or PC and it's right there, packed lobbies and full servers, like Los Santos never took a day off. Even friends who swore they were done end up drifting back, usually after spotting GTA 5 Accounts for sale...
Perkembangan teknologi digital yang sangat pesat saat ini telah mengubah berbagai aspek kehidupan manusia, termasuk cara kita mencari hiburan secara daring. Berbagai platform digital dan situs hiburan interaktif semakin mudah diakses melalui gawai pintar maupun komputer. Di tengah beragamnya pilihan yang tersedia, istilah pgwin138 link alternatif kerap menjadi topik yang menarik perhatian para...