 Crypto.
 Σχετικά
 Passport
 Conference call
 send money
 Όρους
 Ιδιωτικότητα
 Sierra market
Strategic Investment Accelerates Global Fiber Infrastructure Capabilities and Next Decade Demand
The relentless acceleration of global bandwidth consumption has created unprecedented momentum, transforming the global Optical Communications Market Growth trajectory into one of the most resilient segments across the broader telecommunications hardware and services sector. Driven primarily by the worldwide rollout of standalone fifth-generation mobile networks, rapid cloud migration, and distributed machine learning fabrics, network architectures require constant physical capacity upgrades. Unlike older communication standards where infrastructure upgrades could be achieved through modest software patches or incremental base station tweaks, current capacity bottlenecks can only be solved by deepening optical fiber penetration. Mobile backhaul and midhaul connections between radio access nodes and central data hubs rely entirely on high-capacity fiber lines to support ultra-reliable low-latency communications. Consequently, mobile operators and infrastructure funds are deploying substantial capital into dense dark fiber acquisition, wavelength leasing, and optical transport network equipment. This sustained capital expenditure cycle ensures that transmission hardware suppliers, system integrators, and testing equipment manufacturers will witness elevated order books across multi-year modernization initiatives.
A primary catalyst accelerating this upward market curve is the massive structural investment flowing into hyperscale data center construction. Massive technology conglomerates are constructing warehouse-sized data campuses globally, each requiring millions of intra-rack and inter-facility fiber connections to function as unified compute engines. High-performance computing clusters dedicated to generative AI training routines demand ultra-broadband, non-blocking network fabrics where individual computing blades exchange immense data volumes simultaneously. In this intensive operating environment, copper interconnects become impractical beyond distances of a few meters due to signal attenuation and immense heat generation. Photonic switches, active optical cables, and multi-lane transceivers have therefore become mandatory architectural components inside the data center fabric. Beyond individual campus boundaries, data center interconnect systems utilizing dense wavelength division multiplexing are experiencing rapid revenue expansion, allowing geographically separated availability zones to mirror workloads seamlessly with millisecond latency. The persistent proliferation of software-as-a-service platforms, video streaming platforms, and distributed cloud computing guarantees steady demand for these high-performance photonic connectivity solutions.
Simultaneously, government-backed universal broadband initiatives across North America, Europe, and developing Asian economies are providing durable tailwinds for physical network installations. Recognizing that equitable high-speed internet access directly impacts national economic productivity, legislative bodies have committed tens of billions in public funding to eliminate digital disparities. These initiatives primarily prioritize fiber-to-the-home rollouts over wireless or satellite alternatives, acknowledging fiber as the only true future-proof transmission technology capable of scaling across decades. Subsidized deployment programs are driving massive procurements of passive optical network hardware, optical line terminals, ruggedized field enclosures, and field-splicing equipment. As regional internet service providers and rural cooperatives secure grant capital to expand their footprints, equipment manufacturers are enjoying stable revenue pipelines independent of cyclical commercial enterprise spending patterns. The convergence of consumer broadband modernization and enterprise fiberization creates a balanced demand profile that cushions suppliers against short-term economic downswings.
Looking toward the remainder of the forecast period, overall market expansion will increasingly be governed by software-defined optical networking and automated transmission provisioning. As optical meshes expand to encompass thousands of dynamic wavelengths across intercontinental spans, manual operational reconfigurations become prohibitively expensive and error-prone. Modern service providers are embracing reconfigurable optical add-drop multiplexers combined with intelligent software controllers that automatically adjust spectral routing based on real-time traffic demand. These intelligent, automated control planes lower operational expenditures, reduce power consumption, and allow telecommunication carriers to offer bandwidth-on-demand services to enterprise clients. Furthermore, ongoing research into co-packaged optics architectures promises to integrate optical engines directly alongside processing silicon, eliminating lossy circuit board traces and setting the stage for future generational market expansion. Bolstered by unceasing digital connectivity needs and robust hardware innovation, the optical communications sector is well-positioned for enduring commercial expansion.
Top Trending Reports :
Cybersecurity Consulting Services Market
Data Backup And Recovery Services Market
Data Center Design And Consulting Services Market
Data Science And Big Data Education Services Market
Debt Restructuring Advisory Services Market
Bub
Do?

Κατηγορίες
Διαβάζω περισσότερα
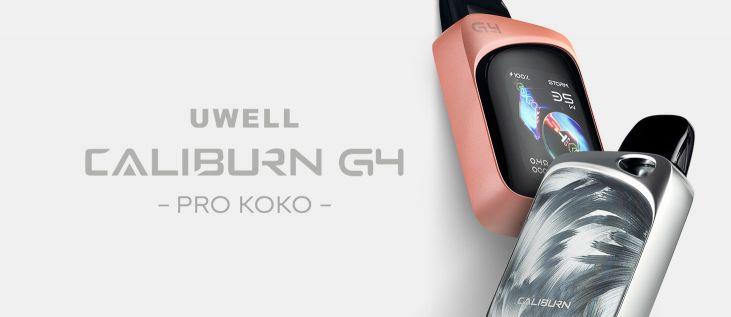
The Uwell Caliburn G4 Pro Koko Pod Kit has quickly become one of the most sought-after pod systems on the market. Known for its sleek design, long-lasting battery, and advanced features, it caters to a wide range of vapers—from beginners to experienced users. This comprehensive guide explores every aspect of the device, from design and build quality to performance, pods, and usability,...
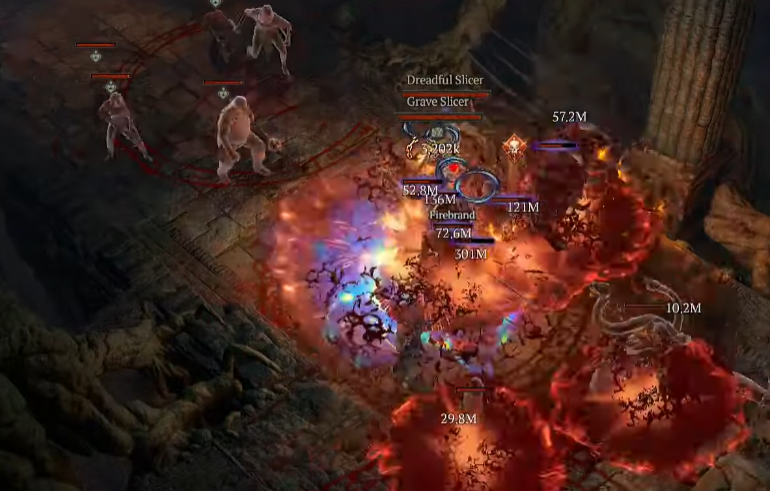
Diablo IV gold has taken the action RPG world by storm, and the Druid has quickly emerged as one of the most versatile and powerful classes for players aiming to push high-level content. With shapeshifting abilities, devastating nature-based spells, and summoning powers, the Druid can handle hordes of enemies, elite bosses, and intense endgame encounters. If your goal is to maximize damage,...
The kingdom of Pharloom had barely settled into its rhythm when Team Cherry spoke again. It was the first week after Hollow Knight: Silksong finally escaped into the wild, and players were still counting their deaths against Moorwing. That first patch had arrived like a merciful hand, trimming the thorns for the early game. But the second patch, numbered 1.0.28626, carried a different message:...
Roboterhilfe in Genshin In Genshin Impact begegnen Sie der Besitzerin der Krumkake-Werkstatt, Dzin-Klats, die westlich von Naschgorod lebt. Ihre Aufgabe besteht darin, ihr bei der Reparatur ihrer einzigartigen Abfallsortiergeräte zu helfen. Dabei entdecken Sie, wie ein gewöhnlicher Roboter mit der Festung Meropidas zusammenhängt. Dies markiert den Beginn einer spannenden Suche,...
In the fast-moving world of modern streetwear, few names capture attention quite like Carsicko. The brand has developed a distinctive identity built around bold graphics, contemporary silhouettes, and the raw energy associated with youth culture. More than simply clothing, Carsicko represents a style that blends confidence, individuality, and the visual language of today’s urban...